OSHAWA REAL ESTATE MARKET REPORT · As of September 22, 2026What 717 Active Listings Tell Buyers, Sellers & Investors in Oshawa Right NowLive. Work. Invest. Belong. Local market insight,
Dated: December 29 2025
Views: 127
Buying your first home in Ontario has never been more closely tied to one factor: mortgage rates.
As we move into 2026, first-time homebuyers across the GTA, Durham Region, Hamilton, and Kitchener-Waterloo are asking the same critical questions:
This refreshed guide provides clear, practical insight—not speculation—based on current economic signals and lender behaviour, helping first-time buyers make confident, informed decisions.
Stability, not dramatic cuts.
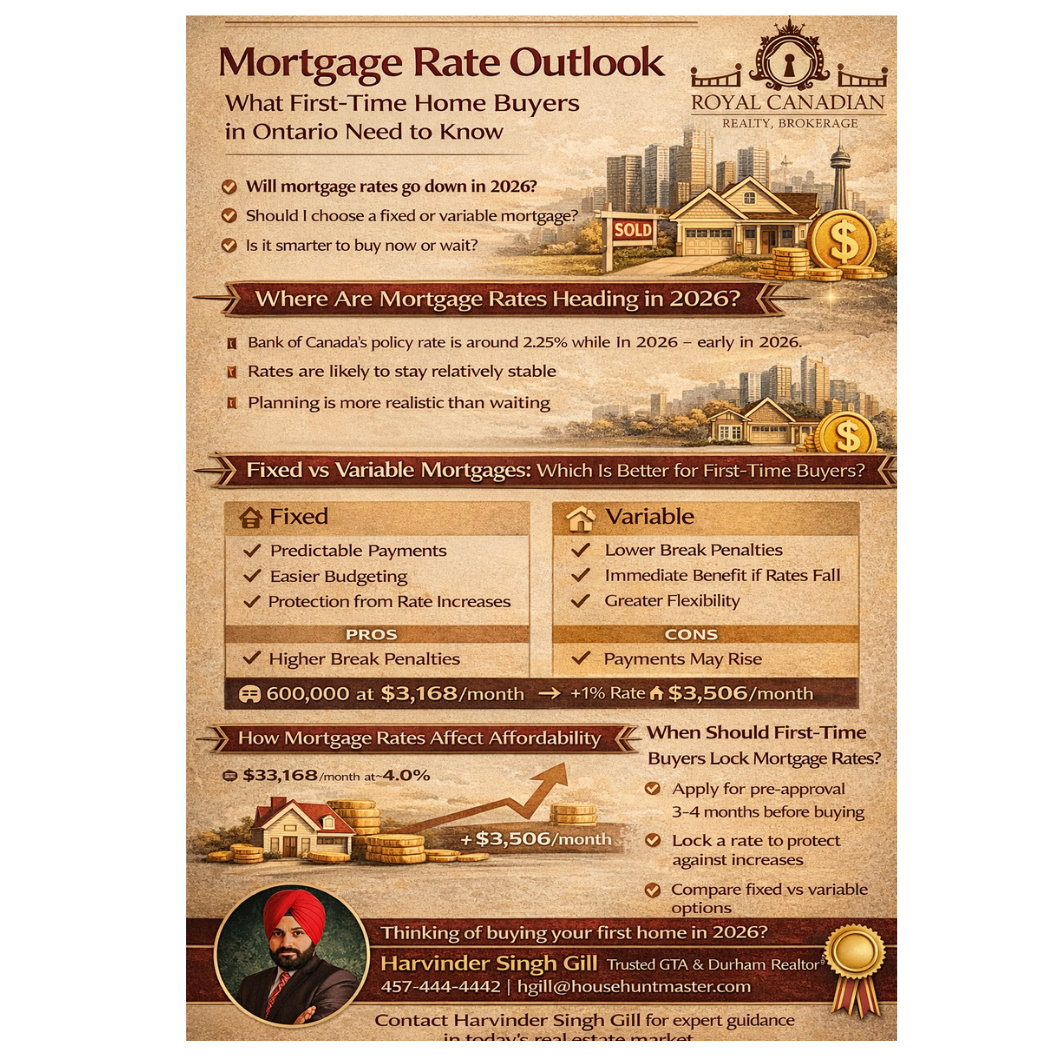
According to current guidance, mortgage rates in Canada are expected to remain relatively steady through early 2026, with the possibility of modest upward pressure later in the year.
The Bank of Canada's policy rate, currently around 2.25%, has been described as "about the right level" to keep inflation near its target.
Key Insight: For buyers, the focus should shift from "when will rates fall?" to "am I financially ready to buy?"
Mortgage rates are influenced by two main forces:
There is no one-size-fits-all answer, but risk tolerance and cash flow matter more than the headline rate.
Why Many First-Time Buyers Prefer Them
Fixed rates remain popular with first-time buyers who need certainty, especially in higher-priced markets like Toronto, Mississauga, and Durham.
Who They're Best For
Variable mortgages may suit buyers with strong incomes, savings buffers, and flexibility, but they are not ideal for tight budgets heading into 2026.
Even small interest rate changes have a major impact on affordability.
A mortgage around $600,000 at ~4.0%
≈ $3,168/month
The same mortgage at ~5.0%
≈ $3,506/month
Difference:
Over $300 more per month
Waiting only for rates to drop can be risky.
Many buyers may find that entering the market sooner—while prices remain relatively soft—offers better long-term affordability, especially with the option to refinance later.
Most Canadian lenders offer 90–120 day rate holds, which can be a powerful tool.
Instead of predicting rates, focus on readiness:
Preparation gives you control, regardless of where rates move.
Large drops are unlikely. Stability is the more realistic expectation based on current Bank of Canada guidance and economic conditions.
Fixed mortgages often suit buyers who need payment certainty; variable may work for higher-income buyers comfortable with risk and payment fluctuations.
Waiting can backfire if prices rise. Readiness and long-term affordability matter more than perfect timing.
Often several hundred dollars per month for typical GTA-area mortgages. On a $600,000 mortgage, a 1% increase adds approximately $338/month.
A rate hold locks in today's rate for 90-120 days while you shop for homes. It's a smart strategy that protects you from rate increases while allowing you to benefit if rates drop.
The 2026 mortgage environment is not about chasing the lowest rate—it's about making informed, sustainable decisions.
Buying your first home is one of the biggest financial decisions you'll ever make. My approach is simple:
No pressure, no hype—just straightforward advice based on your situation and the current market reality.
I believe informed buyers make better decisions. I'll help you understand your options, not push you into a sale.
We'll focus on your long-term affordability and goals, not trying to time the market perfectly.
Reach out to Harvinder Singh Gill today for clear guidance, practical planning, and a confident path forward.
Royal Canadian Realty
Your trusted partner for first-time homebuyers across the GTA & Durham Region
Serving: Peel Region & West GTA
Unit 1 - 2896 Slough St
Mississauga, ON L4T 1G3
Serving: York Region, Durham Region & North/East GTA
Suite 206 - 3 Centre St
Markham, ON L3P 3P9
Serving: Waterloo Region
Suite 2B - 625 King St E
Kitchener, ON N2G 2M2
Serving: Hamilton-Burlington
Suite 300 - 163 Centennial Pkwy N
Hamilton, ON L8E 1H8
Let's turn your first-time homebuying dreams into reality—with smart planning and expert guidance.
OSHAWA REAL ESTATE MARKET REPORT · As of September 22, 2026What 717 Active Listings Tell Buyers, Sellers & Investors in Oshawa Right NowLive. Work. Invest. Belong. Local market insight,
OSHAWA & DURHAM REGION REAL ESTATE · September 17, 2026Fed Raises Rates... Will the Bank of Canada Follow? What It Could Mean for Home Buyers, Sellers and InvestorsSame market. Smarter
NEWMARKET, ONTARIO · Investor & Renovator ListingInvestor & Renovator Special in Newmarket: Great Potential in a Prime LocationRenovate. Reimagine. Add Value. A spacious detached
OSHAWA FIRST-TIME BUYER GUIDE · Week of September 14, 20267 Things Oshawa First-Time Home Buyers Are Asking This WeekReal buyer stories, honest rate advice, a free checklist and a process
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Markham may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 1:03 AM UTC
Show More...

The listing data displayed is deemed reliable but is not guaranteed accurate by CREA®. Data last updated on September 22, 2026 1:41 AM UTC The trademarks REALTOR®, REALTORS®; and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA®) and identify real estate professionals who are members of CREA®. Used under license. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by The Canadian Real Estate Association (CREA®) and identify the quality of services provided by real estate professionals who are members of CREA®. Used under license.
Show More...